Key Notes
- Tesla reported adjusted EPS of $0.48, above the $0.45 company-compiled consensus, while $28.05 billion in revenue produced different comparisons across analyst surveys.
- Reported net income fell 43% to $787 million as higher operating expenses outweighed improved gross margins, leaving an operating margin of 2.6%.
- Free cash flow recovered to $1.53 billion after a negative second quarter, and Tesla ended September with $45.45 billion in cash and short-term investments.
Tesla Inc. (NASDAQ: TSLA) reported adjusted third-quarter earnings of $0.48 a share, beating the $0.45 average in its company-compiled analyst survey, as revenue reached $28.05 billion. Shares rose in early after-hours trading despite a sharp decline in reported profit.
The October 21 shareholder update presents a mixed quarter: revenue was roughly unchanged from a year earlier, automotive sales weakened and operating expenses increased. Free cash flow returned to positive territory, giving Tesla more room to fund its expanding AI, robotics and manufacturing programs.
TSLA traded at $391.43, up 1.28% from its $386.47 regular-session close, in CNBC’s quote at 20:21 UTC. The stock had gained 3.41% during the regular session; the additional rise is an early extended-hours snapshot.
Adjusted Earnings Beat as Revenue Expectations Diverge
Tesla’s $0.48 adjusted EPS exceeded the $0.45 average and median in its October 19 consensus, compiled from 23 sell-side analysts. Revenue of $28.046 billion fell short of that survey’s $28.341 billion average and $28.264 billion median.
A different survey produces a different revenue comparison. CNBC’s report cites LSEG estimates of $0.43 in adjusted EPS and $27.9 billion in revenue, both below Tesla’s actual results. The figures should therefore be assessed against an identified benchmark, rather than described as a universal sales beat or miss.
On a GAAP basis, Tesla earned $0.22 a diluted share, down from $0.39 a year earlier. Net income attributable to common shareholders fell 43% to $787 million. Adjusted net income was $1.70 billion, down 4%.
The gap reflects exclusions including stock-based compensation, unrealized digital-asset and investment gains or losses, and certain tax items. Adjusted EPS helps compare the underlying business across quarters, but it does not replace the reported earnings figure.
Higher Expenses Offset Stronger Gross Margins
Operating income fell 56% to $718 million, leaving a 2.6% operating margin, compared with 5.8% a year earlier. Operating expenses rose 39% to $4.78 billion as Tesla increased spending on AI and other research projects, compensation and administration.
That decline came even as total gross margin improved to 19.6% from 18.0% a year earlier and 16.8% in the second quarter. Automotive gross margin excluding regulatory credits reached 18.1%, up from 15.4% a year earlier.
The distinction is significant for shareholders. Tesla improved the margin earned before operating expenses, but those additional expenses absorbed the benefit. A stronger manufacturing margin did not translate into stronger companywide operating profit.
Automotive revenue declined 3% to $20.56 billion. Tesla cited lower vehicle selling prices, changes in sales mix, fewer deliveries and reduced regulatory-credit revenue among the pressures on sales.
Free Cash Flow Recovers Despite Heavy Investment
Tesla generated $6.26 billion in operating cash flow and spent $4.73 billion on capital investment, producing $1.53 billion in free cash flow. That reverses the second quarter’s $1.09 billion cash outflow after investment.
The recovery partly reflects lower capital expenditure than the previous quarter’s $5.79 billion. Investment spending nevertheless more than doubled from a year earlier, while free cash flow remained 62% below the comparable 2025 quarter.
Cash, cash equivalents and short-term investments totaled $45.45 billion at quarter-end, up from $43.52 billion in June. The larger liquidity balance provides funding flexibility as Tesla builds computing capacity, battery operations and new production programs.
For TSLA investors, the next question is whether cash generation can remain positive as those projects expand. One quarter of recovered free cash flow does not establish the eventual cost or return of Tesla’s AI and robotics investments.
Deliveries Slip While Services Expand
Tesla’s earlier operating update recorded 486,532 deliveries and production of 464,391 vehicles. Deliveries were 2% lower than a year earlier, with Model 3 and Model Y accounting for 478,237 customer handovers.
Energy-storage deployments increased 10% to 13.7 gigawatt-hours, but energy revenue fell 16% to $2.88 billion. Tesla attributed part of the revenue decline to tariff-related customer refunds, illustrating why deployment volumes alone do not determine financial results.
Services and other revenue rose 33% to $4.61 billion. Tesla also reported 1.74 million active Full Self-Driving subscriptions under a definition that includes both upfront purchases and monthly subscriptions, excluding free trials. That figure should not be read as a count of monthly subscribers alone.
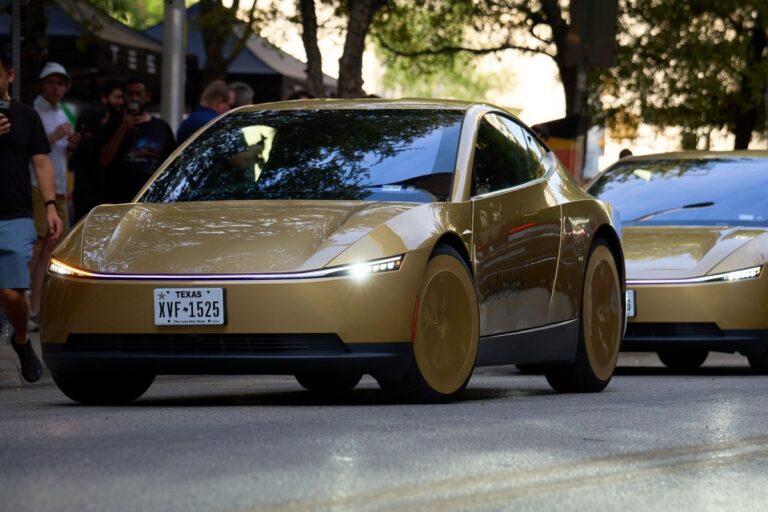
The company said Cybercab Robotaxi rides began in Austin in September. Progress in that service remains distinct from consumer FSD (Supervised), which still requires active driver supervision and does not make a privately owned vehicle autonomous.
Product Execution and Merger Review Shape the Outlook
Tesla’s outlook emphasizes using existing factory capacity, maintaining liquidity and expanding software and fleet-based profits. Future deliveries depend on demand, supply-chain readiness and how vehicles are allocated between customer sales and Tesla’s own fleet.
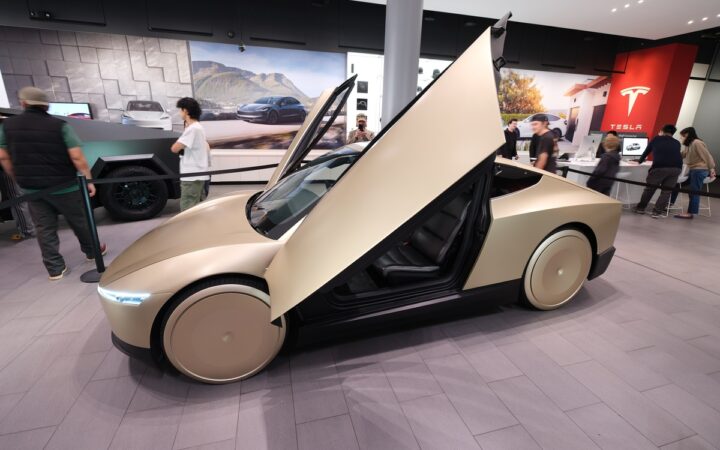
The company said Semi production in Nevada and Optimus production in Fremont have begun. The Roadster remains in design and development in its capacity table. As we previously reported, reservations do not guarantee delivery or establish a completed vehicle order.
Separately, Tesla and SpaceX have formed independent committees to explore a possible merger, as we reported. No transaction terms have been agreed, and the review does not establish that a deal will happen.
The earnings release gives TSLA shareholders a more immediate financial test: sustaining gross-margin improvement and positive cash flow while controlling the expenses attached to Tesla’s next generation of products.