Key Notes
- SPCX rose more than 10% in early premarket trading after SpaceX reported its first quarterly profit since the June IPO, reversing the previous quarter’s loss.
- SpaceX earned $4.4 billion on $14.58 billion in revenue, with Starlink’s Connectivity segment contributing more operating profit than the larger AI business.
- Independent committees are exploring a potential Tesla merger, but no terms are agreed and heavy infrastructure spending remains a separate consideration for shareholders.
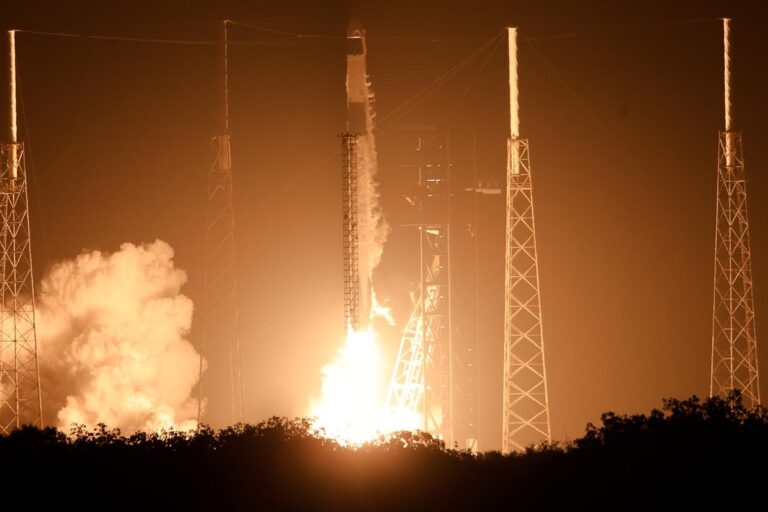
Space Exploration Technologies Corp. (NASDAQ: SPCX) shares jumped more than 10% in premarket trading Wednesday after SpaceX delivered its first quarterly profit since its June IPO and Elon Musk confirmed that independent committees are exploring a possible merger with Tesla Inc. (NASDAQ: TSLA).
SPCX traded at $163.60 at 04:42 a.m. Eastern time, or 08:42 UTC, up $15.81, or 10.7%, from Tuesday’s $147.79 close, according to Nasdaq last-sale data displayed on CNBC’s quote page. The move extended earlier gains of roughly 9%; it is a premarket snapshot, rather than a regular-session closing return.
The reaction follows results showing $4.404 billion in net income and $14.575 billion in revenue for the quarter ended September 30. The financial turnaround and merger review give shareholders two separate developments to assess: stronger current earnings and the possibility of a substantially different corporate structure.
First Post-IPO Profit Reverses the Previous Quarter’s Loss
SpaceX’s earnings release reports diluted profit of $0.35 a share, compared with a $1.054 billion net loss a year earlier. Revenue increased 161% from the same period in 2025.
The previous quarter had produced a $541 million loss, according to the company’s June filing. That makes the September result the first profitable quarterly report of SpaceX’s public-market life, rather than evidence that it had never earned a quarterly profit before listing.
As we reported, the revenue result also exceeded the $12.72 billion LSEG consensus. Wednesday’s stock move is the subsequent market response to that report and Musk’s accompanying comments.
The quarter does not erase the entire year’s losses. Consolidated net loss for the first nine months was $413 million, reflecting the weaker results recorded before the September turnaround.
Operating Earnings Explain Only Part of Net Income
Income from operations was $2.791 billion, below the $4.404 billion net-profit total. The difference matters when assessing how much of the improvement came from selling services and operating the business.
The accounts also show $873 million of interest income, $1.025 billion of other income and a $390 million income-tax benefit, alongside $675 million in interest expense. Those items help reconcile operating earnings with the larger bottom-line result.
They do not negate the operating turnaround. They do mean that treating all $4.4 billion as recurring profit from launches, satellite subscriptions and AI services would overstate what the operating line establishes.
The next test is whether stronger sales continue to support operating profitability as infrastructure, research and acquisition-related costs evolve. One profitable quarter provides evidence of progress without settling the longer-term earnings trajectory.
Starlink Supplies Profit While AI Leads Revenue
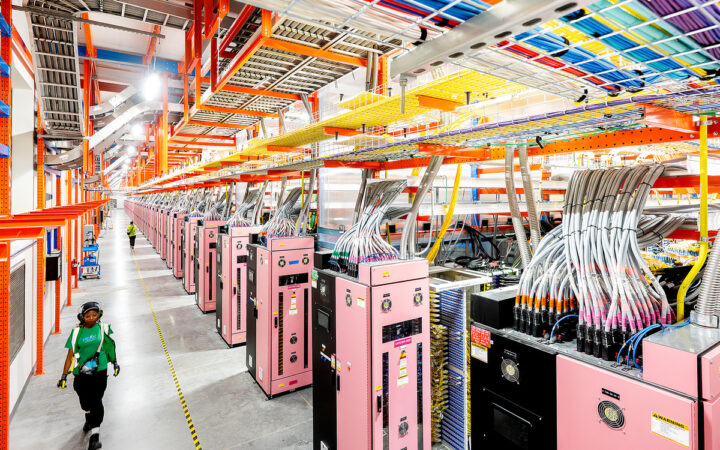
The Super Intelligence segment became SpaceX’s largest revenue contributor, generating $7.56 billion. Connectivity, which includes Starlink, produced $5.248 billion in sales and remained the larger operating-profit contributor.
Connectivity earned $2.367 billion from operations, compared with $431 million for Super Intelligence. The Space segment was close to break-even, with a $7 million operating loss.
That mix gives the stock a different financial profile from a pure launch-services business. AI infrastructure is driving the largest sales contribution, while the satellite network supplies much of the operating earnings supporting expansion elsewhere.
Investors therefore need to assess both businesses. Continued AI revenue growth matters, but so does converting that growth into earnings; Starlink’s contribution depends on sustaining the economics of its expanding subscriber and enterprise base.
Tesla Merger Committees Add a Separate Catalyst
Musk disclosed the independent committees during SpaceX’s October 20 earnings call. As we previously reported, he supports the strategic idea but is excluded from the discussions because he is a conflicted party.
No transaction terms have been agreed. There is no announced purchase price, share-exchange ratio or definitive completion date, and Musk said shareholder support would be necessary.
The proposed rationale spans AI, chip development, robotics and connectivity. Those potential benefits remain a strategic argument; the committees still have to determine whether a specific transaction would serve their respective shareholders.
For SPCX holders, a share-funded deal would require weighing the business acquired against dilution. For TSLA holders, the consideration offered and the rights attached to any replacement shares would be central. The current rally does not answer those valuation questions.
Capital Spending Keeps Cash Generation in Focus
SpaceX spent $19.593 billion on capital expenditure in the third quarter, including $16.444 billion in Super Intelligence. The scale of that buildout remains important even after the return to profit.
For a consistent period comparison, the cash-flow statement shows $13.097 billion of operating cash inflow during the first nine months against $48.069 billion of property, plant and equipment purchases over those same nine months. Quarterly profit and cumulative investment spending measure different things.
The figures show why profitability does not automatically make the expansion self-funding. Shareholders will be watching whether additional capacity produces enough future operating cash to support the investment program.
Tesla’s own results are due after Wednesday’s closing bell, providing the next financial checkpoint for the other company involved in the merger review. For now, SPCX’s premarket advance reflects a sharp earnings improvement alongside a corporate proposal whose terms remain unresolved.