Key Notes
- SpaceX is reportedly finalizing $40 billion in debt financing, with rates around 8.3% on the lowest-rated portion and about 7.75% on a chip-backed portion.
- Apollo and Goldman Sachs are leading the transaction, with final pricing expected next week and terms still subject to change.
- Official results show infrastructure purchases exceeding operating cash generation, keeping financing costs central to the SPCX investment case.
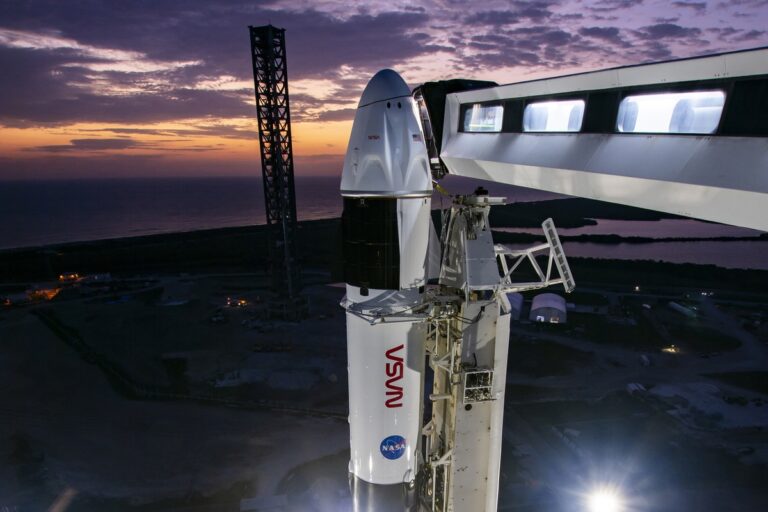
SpaceX (NASDAQ: SPCX) is finalizing a $40 billion debt financing at higher borrowing costs, with rates on part of the package potentially reaching about 8.3% as investors reassess artificial-intelligence infrastructure risk.
Semafor reported the prospective pricing on October 22, citing people familiar with the transaction. Apollo Global Management Inc. (NYSE: APO) and Goldman Sachs Group Inc. (NYSE: GS) are leading the deal, which is expected to be finalized next week, although pricing could change.
The development shifts the focus from whether SpaceX can arrange a large financing to what lenders will charge for it. Stronger quarterly earnings provide one part of the credit picture; the cost and pace of new computing investment provide another.
Two Debt Portions Face Different Pricing
The lowest-rated portion is expected to carry an interest rate around 8.3%. A safer portion backed by some of SpaceX’s chips could price near 7.75%, Semafor reported. Apollo and Goldman declined to comment.
The report puts the prospective 7.75% pricing more than one percentage point above the level at which existing SpaceX bonds trade. That comparison concerns the cost of the new financing relative to outstanding debt, rather than a finalized coupon across the entire $40 billion package.
The difference is financially meaningful at this scale. As a simple sensitivity calculation, an extra percentage point applied to $40 billion would equal $400 million in annual interest. That is an illustration of the amount at stake, not an estimate of SpaceX’s actual additional bill: the allocation between debt portions, final terms and fees remain necessary to calculate that.
The 8.3% figure also should not be applied automatically to the full transaction. Different claims on collateral and different positions in the repayment structure can produce materially different prices within the same financing.
AI Spending Keeps Funding Needs Elevated
We previously reported that SpaceX was discussing financing to buy chips from Nvidia Corp. (NASDAQ: NVDA). The latest report adds prospective borrowing costs to that earlier account; it does not establish that the funds have been received or the chip purchases completed.
SpaceX’s official quarterly release helps explain the requirement. Third-quarter revenue reached $14.575 billion, while capital expenditure totaled $19.593 billion. The Super Intelligence segment accounted for $16.444 billion of that investment, making computing the dominant part of the spending program.
The group reported $4.404 billion in net income for the quarter. However, accounting profit and cash available after infrastructure investment measure different things. Over the first nine months, operating activities generated $13.097 billion, while purchases of property, plant and equipment used $48.069 billion.
The difference between those two nine-month cash-flow lines was approximately $34.97 billion. It is a comparison of operating cash generation with equipment and property purchases, rather than a complete measure of the change in cash, which also reflects financing, securities transactions and other investing activity.
Chip Collateral Does Not Remove Lending Risk
Equipment backing gives lenders an asset claim, but its value still depends on the contractual protections and the assets’ usefulness over the life of the borrowing. Computing hardware can generate revenue while also depreciating and facing competition from newer technology.
That makes deployment speed, utilization and customer payments relevant alongside the number of processors acquired. Capacity installed ahead of demand has different cash economics from equipment already serving a contracted customer.
SpaceX’s existing bonds have weakened and the cost of default protection has widened, according to Semafor. Those are signals of a higher market price for credit risk, rather than evidence that the company has defaulted or that the proposed financing has failed.
The distinction also applies to stronger AI demand. More orders can support the case for new capacity, but lenders must still assess when that demand becomes cash and whether it can cover interest, repayment and future equipment replacement.
What the Financing Means for SPCX Investors
The transaction would add repayment obligations without issuing shares directly through this financing. For equity holders, that makes the eventual return on the funded assets and the burden of servicing the debt important to evaluating the expansion.
SpaceX is separately exploring a combination with Tesla Inc. (NASDAQ: TSLA), as we reported. No definitive merger agreement or exchange ratio has been announced. A possible combination should therefore not be treated as an agreed solution to the financing requirements.
The next material disclosures are the final size and pricing of each debt portion, maturity dates, collateral protections and any guarantees. Those details will determine how the financing affects cash costs and the claims on future earnings. Until the deal is finalized, the reported rates remain indications of where negotiations stand.