Key Notes
- Barclays sees a possible Tesla–SpaceX merger announcement ahead of the annual meeting it expects by December 6.
- The bank views SpaceX as the likely acquirer in an all-stock deal, with no agreed terms announced.
- Existing investment and AI infrastructure ties provide context, while governance and approvals remain unresolved.
Tesla Inc. (NASDAQ: TSLA) and Space Exploration Technologies Corp. (NASDAQ: SPCX) could announce a merger ahead of Tesla’s annual shareholder meeting, according to Barclays, which views SpaceX as the more likely buyer in an all-stock transaction.
The scenario puts both sets of shareholders in focus as Elon Musk’s automotive, aerospace and artificial-intelligence businesses become more closely connected. It remains an analyst assessment: neither company has announced a definitive Tesla–SpaceX merger agreement or an agreed share-exchange ratio.
Analysts led by Dan Levy outlined the possibility in an October 14 client note, Bloomberg reported. The bank expects Tesla’s meeting by December 6 at the latest, making an announcement ahead of that gathering one potential route rather than a guaranteed year-end deadline.
Barclays Identifies Two Possible Timelines
An announcement tied to the annual meeting could bring the proposed combination before shareholders sooner. Barclays warned, however, that a late-October or early-November announcement would leave a more difficult timetable for obtaining approval at that meeting, according to Investing.com’s account of the research.
The alternative is a separate announcement within six to 12 months. The distinction is between a possible announcement and a completed transaction; an autumn disclosure would not mean that the companies had already combined.
The merger discussion also predates this week’s note. As we previously reported, Musk had reportedly discussed a potential combination ahead of SpaceX’s IPO. Barclays is adding a possible structure and timetable to that debate.
What an All-Stock Deal Would Mean
Barclays considers SpaceX the likely acquirer, with Tesla shareholders receiving SpaceX shares rather than cash. Its scenario allows for a premium to Tesla’s market value, but that is a modeling assumption, not an offer made to TSLA holders.
The exchange ratio would determine how much of the combined business each Tesla share buys. A headline premium would need to be assessed alongside the value of the shares received, the number of new shares issued and the voting rights attached to them.
For existing SPCX investors, the same transaction would expand the business they own while diluting their percentage interest. Whether that trade-off creates value would depend on the price paid for Tesla and the cash flows the combined operations could generate.
An equity-funded purchase would avoid paying the entire acquisition price in cash. It would not eliminate the financing needed for factories, chips, AI infrastructure or other operating commitments after a merger.
AI Infrastructure Provides the Strategic Rationale
Barclays’ investment case centers on closer integration of AI technology, including Tesla’s robotics and autonomous-driving ambitions with SpaceX’s AI operations. The appeal is coordination across software, computing hardware and physical products, rather than simply placing a carmaker beside a rocket business.
There is already a documented infrastructure link. SpaceX’s IPO disclosures described a framework agreed with Tesla for developing the Terafab chip-manufacturing initiative. They also said specific projects, development schedules and capital commitments would require separate negotiations and agreements.
That distinction leaves considerable execution work even where the strategic ambition is shared. A combined company might simplify decisions about allocating resources, but it would still have to manufacture competitive chips and deliver useful AI products at an acceptable cost.
Tesla’s first-quarter update likewise documented the expansion of its own AI training infrastructure, including Cortex 2 beginning training workloads. These investments illustrate why access to computing capacity is part of the wider corporate discussion.
Financial and Engineering Ties Already Exist
Tesla’s amended annual filing provides a concrete financial connection. The company completed an approximately $2 billion investment in SpaceX Class A shares on March 12, after its earlier right to invest in xAI was converted following SpaceX’s February acquisition of xAI Holdings.
The filing also describes commercial relationships between the businesses. Tesla recognized approximately $143.3 million in revenue from SpaceX in 2025, primarily from vehicle sales, and reported expenses under commercial, licensing and support arrangements.
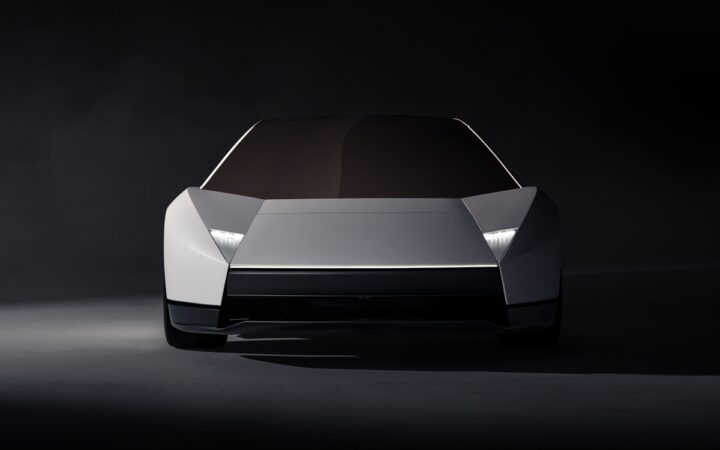
Engineering cooperation has become more visible too. As we reported, Tesla’s October 15 Roadster presentation featured technology developed with SpaceX and a production target of 2028. The demonstration showcased collaboration without announcing a corporate merger.
Those existing relationships show that cooperation can proceed while the companies remain separate. A transaction would need to explain the additional financial or operational benefit of common ownership beyond arrangements already in place.
Voting Control and Approvals Remain Central
Governance would be a major issue for outside shareholders. SpaceX’s offering disclosures give Class B stock 10 votes per share and Class A stock one, illustrating why economic ownership and voting control must be considered separately in any proposal.
Barclays also flagged board and shareholder approvals, competition review and national-security considerations as potential obstacles. Its suggested buyer and payment structure do not resolve those questions or establish that negotiations are under way.
For TSLA and SPCX holders, the next meaningful evidence would be a company announcement setting out actual terms, the exchange ratio, governance arrangements and the approval process. Until then, the prospect remains a high-profile merger scenario supported by growing business ties, rather than a signed deal.