Key Notes
- Jensen Huang expects the AI stock selloff to pass as the technology spreads across industries and economies.
- Nvidia’s latest quarterly revenue doubled, while investors are scrutinizing how customers finance new infrastructure.
- CoreWeave’s rising sales and heavy interest expense show why strong AI demand does not eliminate funding risk.
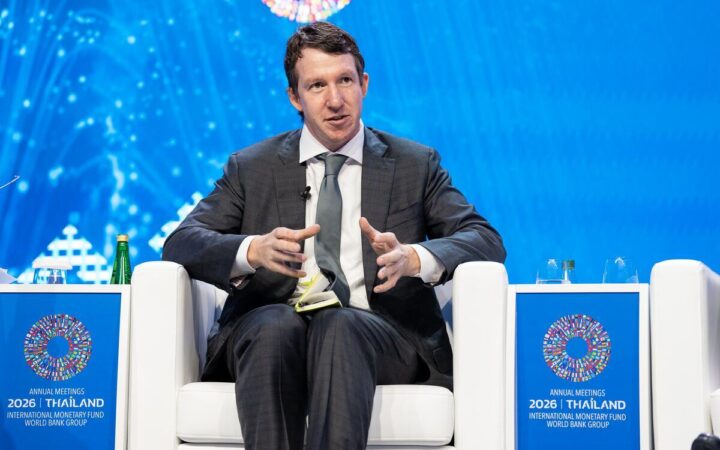
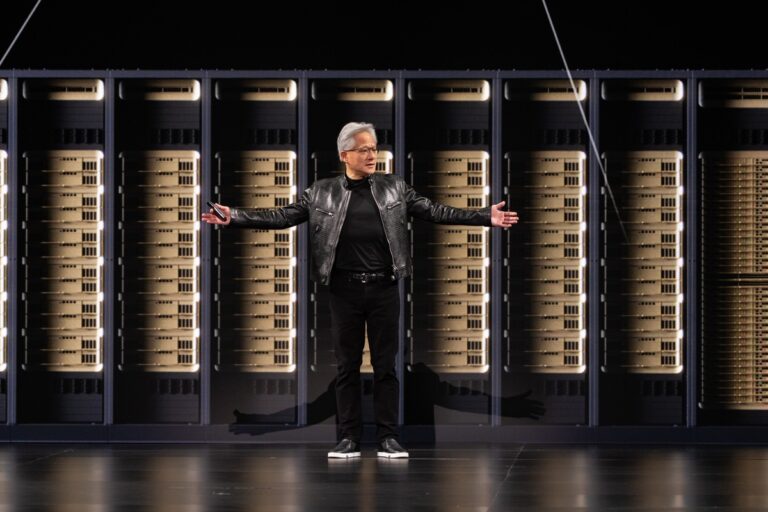
Nvidia Corp. (NASDAQ: NVDA) Chief Executive Jensen Huang sought to reassure investors about the latest AI stock selloff, arguing that the technology’s long-term economic impact will outlast the market’s current anxiety.
“All of this is going to pass,” Huang told Bloomberg’s Emily Chang at an event in Berlin on October 16, the news agency reported. He pointed to AI’s potential to change industries and economies as the reason for his confidence.
For Nvidia shareholders, the remarks address a widening gap between the pace of AI-related sales and investors’ concerns about financing the infrastructure behind them. Huang’s assessment is a statement of confidence in the technology, rather than a timetable for a stock-market recovery.
AI Demand and Financing Face Different Tests
The reassurance follows a difficult week for companies supplying processors and building cloud capacity. As we previously reported, more than $1 trillion was erased from the combined market value of 20 major AI and semiconductor companies during the week through CNBC’s October 15 report.
The selling has brought financing into sharper focus. Computing facilities require substantial spending on chips, buildings and power before all the associated revenue arrives. Strong demand can therefore coexist with pressure on the companies responsible for paying for that expansion.
For NVDA, the distinction matters because customers’ ability to fund projects can affect the timing and scale of equipment purchases. Confidence that AI will be widely used does not, by itself, settle how much investors should pay for the earnings expected from it.
Nvidia’s Earnings Underpin Huang’s Confidence
Nvidia’s most recent completed quarter provides substantial evidence of commercial growth. In its August 26 earnings release, the company reported fiscal second-quarter revenue of $96.2 billion, up 106% from a year earlier and 18% from the preceding quarter.
Data Center revenue reached $89 billion, an annual increase of 117%. GAAP gross margin was 75%, while GAAP earnings per diluted share were $2.46 and adjusted earnings were $2.22. These are results for the quarter ended July 26, not newly released October figures.
As we reported at the time, the results also accompanied the rollout of the Vera Rubin platform. Nvidia’s August outlook called for fiscal third-quarter revenue of $108 billion, plus or minus 2%, without assuming Data Center compute revenue from China.
That forecast remains distinct from reported revenue. The next financial update will help show whether customer demand, delivery schedules and margins continue to support the scale of growth investors have been pricing into the business.
CoreWeave Illustrates the Funding Challenge
CoreWeave Inc. (NASDAQ: CRWV) has become a prominent test of the financing model. On October 15, Huang told reporters in Stockholm that he saw no need for Nvidia to provide a financial backstop, Reuters reported. He also expressed confidence in the company’s financial position.
Those comments came a day before the Berlin remarks. They concern a specific cloud provider and should not be treated as a new financing commitment or a guarantee covering the wider AI sector.
CoreWeave’s own second-quarter results show the tension. Revenue rose approximately 112% to $2.575 billion, but net interest expense reached $640 million and the company recorded a $626 million net loss.
As we previously reported, yields on two CoreWeave bonds approached 15% during the October 14 selloff. Those secondary-market yields reflected falling bond prices; they did not reset the fixed coupons on outstanding notes.
Nvidia Has a Direct Stake in the Buildout
Nvidia is more than a supplier commenting on a customer’s prospects. In a January 26 announcement, it disclosed a $2 billion investment in CoreWeave shares at $87.20 apiece.
The companies also outlined a collaboration intended to accelerate the development of more than 5 gigawatts of AI facilities by 2030. Their plans included using Nvidia’s financial strength to help secure land, power and buildings, alongside adopting multiple generations of its computing technology.
The investment is a completed transaction disclosed in January; the infrastructure expansion is a multiyear objective. Keeping those categories separate is important when assessing how much support has already been provided and what future development still requires.
Industrial Adoption Provides Another Measure
Nvidia continues to point to uses beyond AI chatbots. On October 14, it announced expanded use of its CUDA-X software across semiconductor design, manufacturing and testing, including tools for simulating materials and analyzing inspection data.
Such applications give substance to Huang’s argument that AI can reach across industries. They are not, however, a separate revenue forecast or evidence that every infrastructure project will earn an attractive return.
For Nvidia investors, the practical tests remain customer orders, deployment, margins and cash generation across the ecosystem. Huang expects the turmoil to pass; subsequent financial results and funding conditions will determine how convincingly the industry can support that view.