Key Notes
- Christine Lagarde will step down as ECB president on February 7, 2027, nearly nine months before her eight-year mandate was due to end.
- The European Council will appoint her successor through the treaty process, with no replacement named in the ECB announcement.
- The transition comes amid elevated eurozone inflation, with monetary-policy meetings scheduled for December 17 and February 4 before her departure.
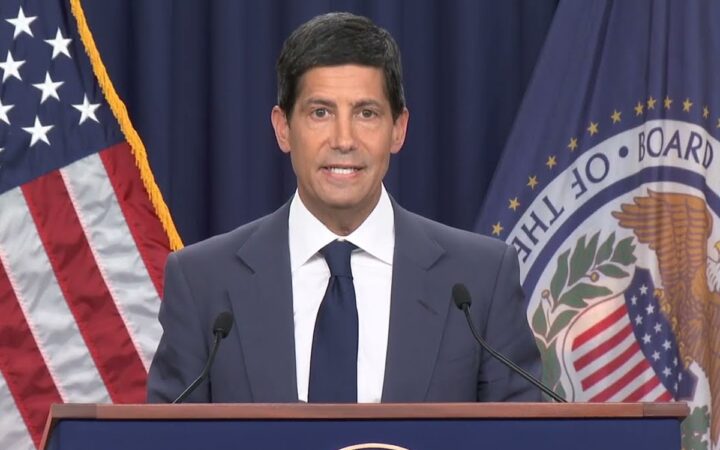
Christine Lagarde will step down as president of the European Central Bank on February 7, 2027, bringing her leadership of the euro area’s monetary authority to an end before her eight-year term was due to expire.
The ECB announced on October 29 that Lagarde had informed its Governing Council and European Council President António Costa of her decision. The statement did not name a successor or give a reason for her departure.
The announcement starts a leadership transition at a time when investors are assessing persistent eurozone inflation and the possibility of further interest-rate increases. The choice of the next president will matter for policy leadership and communication, while rate decisions remain the responsibility of the Governing Council collectively.
February Departure Ends the Mandate Early
Lagarde took office on November 1, 2019, succeeding Mario Draghi. The European Council’s appointment decision gave her a non-renewable eight-year mandate, which would ordinarily run through October 31, 2027.
Her announced exit therefore falls nearly nine months before that scheduled end date. It is a future departure, rather than an immediate vacancy at the central bank.
The ECB said the Governing Council thanked Lagarde and gave her a standing ovation. It did not announce her next role, an interim leadership arrangement or a timetable for naming the next president.
Those omissions leave the succession process as the next institutional step. The confirmed information is the February 7 departure date and the procedure through which European leaders will select a replacement.
European Leaders Will Choose the Successor
The ECB’s release points to Article 283 of the Treaty on the Functioning of the European Union. The European Council, meeting in euro area composition, makes the appointment by reinforced qualified majority.
The Council’s procedure begins with candidates proposed by euro area member states and discussion in the Eurogroup. The Council of the European Union then adopts a recommendation for European leaders.
The European Parliament and the ECB Governing Council are consulted and give their opinions before the European Council adopts the appointing decision. The process therefore involves several institutions; the outgoing president does not personally appoint a replacement.
Executive Board members, including the president, serve non-renewable eight-year terms and must have recognized professional standing in monetary or banking matters. The October 29 announcement did not identify a nominated candidate.
A Leadership Change Does Not Set the Rate Path
The Governing Council comprises the ECB Executive Board and the governors of euro area national central banks. It determines monetary policy and interest rates, so a presidential transition changes the leadership of a collective institution.
Investors will assess the next president’s approach to inflation, economic risks and communication. The appointment alone, however, will not establish whether the ECB raises or lowers rates at a particular meeting.
We previously reported that UBS’s October 19 forecast anticipated quarter-point increases in December 2026 and March 2027, taking the deposit rate to 3%. That was the bank’s forecast, rather than an ECB commitment.
Lagarde’s departure adds a succession question to that outlook. It does not confirm the forecast or demonstrate that the incoming leadership will favor a different policy path.
Inflation Keeps the Policy Challenge in Focus
Eurostat’s final September figures, published October 16, put annual euro-area inflation at 3.8%, up from 3.2% in August. Prices rose 0.6% during the month.
Core inflation, excluding energy, food, alcohol and tobacco, was 2.5% annually. Energy contributed 1.71 percentage points to the headline annual rate, illustrating the pressure from fuel and other energy costs.
As we reported earlier, the gap between headline and core inflation is relevant to assessing the breadth of price pressures. Policymakers must judge whether an energy shock remains concentrated or spreads through wages, services and other prices.
That economic assessment continues through the leadership transition. For bondholders, borrowers and euro investors, incoming data and the Governing Council’s response will remain central alongside the selection of the next president.
The Policy Calendar Continues Through the Transition
The ECB’s meeting calendar schedules monetary-policy decisions for December 17, 2026, and February 4, 2027. The February meeting falls three days before Lagarde’s announced departure.
The next scheduled monetary-policy decision after that is March 18. The calendar provides continuity in the institution’s work, but the departure release did not specify who would lead each stage of the handover.
Lagarde previously served as managing director of the International Monetary Fund from 2011 to 2019 and France’s economy and finance minister from 2007 to 2011, according to her ECB biography.
Her successor will take over an institution facing an unfinished inflation challenge. The immediate milestones are the nomination and appointment process, further details of the transition and the policy decisions still scheduled before February 7.